

Lab-on-a-Chip Market to Reach $709 Million by 2008
By HospiMedica staff writers
Posted on 03 Apr 2003
Augmented public and private sector funding allied with technology, manufacturing, and medical advances are likely to drive global revenues of microfluidics/lab-on-a-chip products from US$127.8 million in 2002 to $709.9 million by 2008, according to a new study from international consultants Frost & Sullivan (London, UK). Posted on 03 Apr 2003
A key driver will be government funding, such as the $4 billion funding increase to the US National Institutes of Health to benefit developers of lab-on-a-chip and prospective clients. A growing number of agencies have been allocating funding for research in the aftermath of 9/11 while boosting end-user demand for bio-defense product applications. The microfluidics industry will also benefit from technologic progress in semiconductors, healthcare, and genomics.
New genome discoveries are stimulating the demand for new diagnostics, which will catalyze the microfluidics sector, although the high price of microfluidics technology may slow adoption. However, the long-term advantages offered by miniaturization, particularly in terms of savings, are supporting use in research and diagnostic settings. Other advantages include increased sensitivity, mobility, and efficiency.
"Since automated labs tend to be more technically advanced and forward thinking, they are more prone to adopt a novel technology. At the same time, open technologies and standards will play a major role in driving this acceptance,” says Frost & Sullivan.
The largest market segment will be DNA/RNA applications, although protein, cell/tissue, and microorganism-detection segments are likely to reduce this sector. With most companies being in the start-up stage, collaborations have been characteristic of the competitive environment, since they enable instant access to skill, intellectual property, or distribution channels.
Related Links:
Frost & Sullivan


Platinum Member
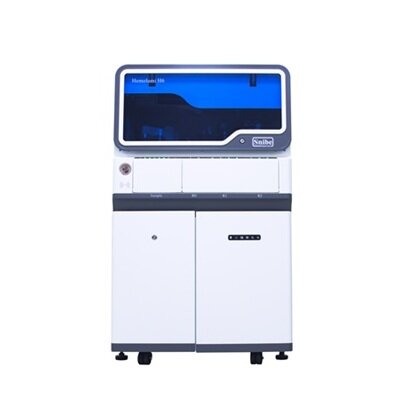
Automated Coagulation Analyzer
Hemolumi H6
CMV CLIA Diagnostic
CLIA CMV IgA Screen Group
Gold Member
Flocked Fiber Swabs
Puritan® Patented HydraFlock®